Key Takeaways
- Removal is not automatic — an independent PCA-protocol inspection should come first.
- Some lenders will consider proceeding in low-risk cases without removal, supported by a PCA report.
- Correctly installed foam in low-risk configurations may not require removal from a purely structural perspective.
- For most homeowners who need to sell, remortgage, or release equity, removal plus RICS certification remains the most dependable route.
- Never remove based on pressure or assumption — inspect first, then decide from evidence.
The Myth of “Always Remove”
A significant portion of the communications around spray foam — from some removal companies, some media coverage, and some well-meaning but uninformed sources — creates an impression that removal is automatic and mandatory. This is not accurate.
The IMA has noted that foam rarely needs removal when it has been correctly installed. RICS guidance is about the inability to inspect the timber — not about the foam being inherently dangerous. The PCA Spray Foam Inspection Protocol exists precisely because there are cases where the risk is low enough that proceeding without removal can be appropriate.
Framing every foam-affected property as requiring urgent, immediate removal is a disservice to homeowners who may have low-risk situations — and can lead to expensive and unnecessary work.
When Removal IS Necessary
There are clear scenarios where removal is the right and necessary course of action:
When the inspection reveals significant risk. If a PCA-protocol inspection finds evidence of wet rot, high timber moisture content, poor installation, or substantially blocked ventilation, removal is necessary — not just for mortgage reasons, but for the physical health of the roof.
When your specific lender requires it. Many mainstream lenders — regardless of inspection outcome — currently require full removal and an RICS certificate before they will lend. If you need to satisfy a specific lender for a sale or remortgage, and that lender requires removal, then removal is your practical necessity regardless of the inspection risk classification.
When you want full, unconditional market access. A removal certificate opens the property to essentially all mainstream lenders. An inspection report only opens a subset. If certainty and breadth of access is your priority, removal is the route.
When equity release is the goal. All equity-release providers currently require full removal. An inspection report is not sufficient in this market segment.
When Removal May Not Be Necessary
There are situations where removal may not be the immediate, necessary action:
When the inspection shows genuinely low risk and your broker identifies a lender willing to proceed on the basis of the report. This is possible — a minority of lenders take this approach — but requires real-time broker intelligence to identify.
When you have no near-term transaction plans and the inspection confirms sound timber and adequate ventilation. In this scenario, monitoring with periodic inspections may be a reasonable approach rather than incurring immediate removal costs.
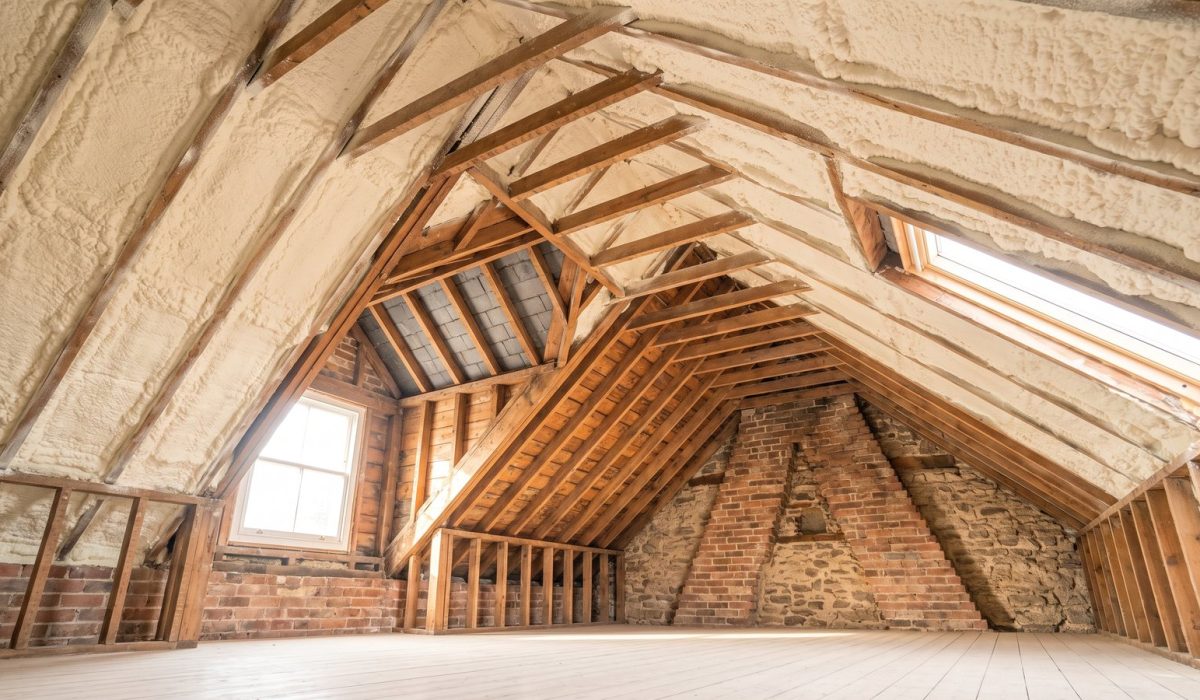
When the foam is in a different location. The mortgage and structural concerns relate specifically to spray foam applied to roof timbers — the sloping rafter surfaces. Foam used in other applications (cavity wall, flat roofs, specific structural contexts) may not create the same surveyor inspection barrier or moisture concerns. Professional assessment of the specific installation is needed.
How Lenders and Inspections Interact
The relationship between inspection outcomes and lender decisions is not formulaic. The same inspection report might:
- Satisfy Lender A (who has adapted their criteria to consider PCA reports in low-risk cases)
- Not satisfy Lender B (who requires removal regardless)
- Prompt Lender C to request removal on specific sections only
This variability is why a specialist mortgage broker — working with current lender knowledge — is essential between the inspection and any removal decision. The inspection establishes facts; the broker translates those facts into lender options.
Deciding Your Route
A practical decision framework:
| Scenario | Recommended action |
|---|---|
| Inspection shows low risk | Consult broker; explore whether a lender will proceed without removal |
| Inspection shows medium/high risk | Proceed to removal |
| Lender specifically requires removal | Proceed to removal |
| Equity release needed | Proceed to removal |
| No transaction in near term; inspection shows low risk | Monitor; review annually; consider removal when transaction looms |
| Unsure | Book inspection first; decide from evidence |
The Bottom Line
Removal is often the right answer — but it is not always the right answer, and it should never be the first action without an independent inspection. Inspect first. Decide from evidence. Act proportionately to the risk and your specific circumstances.
Book an independent PCA-protocol inspection — the starting point, always.
This is general information, not financial advice — please consult a qualified mortgage broker about your circumstances.
Related reading: The PCA Spray Foam Inspection Protocol explained · Mortgage declined due to spray foam? Your next steps · How to choose a spray foam removal company